Weekly Review
The USD rally took a pause during the week starting Monday 5 October. Is it consolidation before another leg of strength? Or has the dollar peaked?
The case for further USD strength: After weeks of strength, it's only natural that some profit taking was due, especially after the recent NFP data. But the FED has noted that one data point doesn't make a trend. Inflation is still too high, it is very likely the FED will hike again before year end and continue hiking in 2027. The Hormuz strait issue looks far from being resolved. And growing 'cost of debt concerns' could give the USD 'safe haven strength'.
The case the USD has peaked: If the Hormuz strait becomes fully operational, the price of oil will fall and inflation expectations will fall with it. Throughout the week, FED board members softened their hawkish narrative a little, tempering very hawkish pricing of future rate hikes. Also throughout the week, a narrative developed that the yield 'sell off' (rising yields) has reached saturation point. And at some point, bonds will become attractive to buy (falling yield).
All things considered, the underlying fundamentals still support a strong USD and until something changes (free flowing oil, softer data, falling inflation), I think dollar pull-backs creating nice support could be a long USD opportunity.
Ultimately, as we are always told, central bank decision are data dependent. So it's all eyes on US CPI data on Wednesday.
In other news, sentiment for the EUR remains subdued, mainly due to political instability in France.
I have read that falling Chinese bond yields is having a knock-on effect on the AUD, which could partly explain the Aussie's weakness this past couple of weeks. As you may know, my general preference is to long the AUD due to its high interest rate, and it does look a little 'oversold'. Will the upcoming week bring an AUD recovery with it?
In amongst the 'high yield, slightly negative overall sentiment', the S&P remains remarkably resilient and it does surprise me that the VIX remains below 20. It does suggest to me that the market isn't too concerned about the long term view.
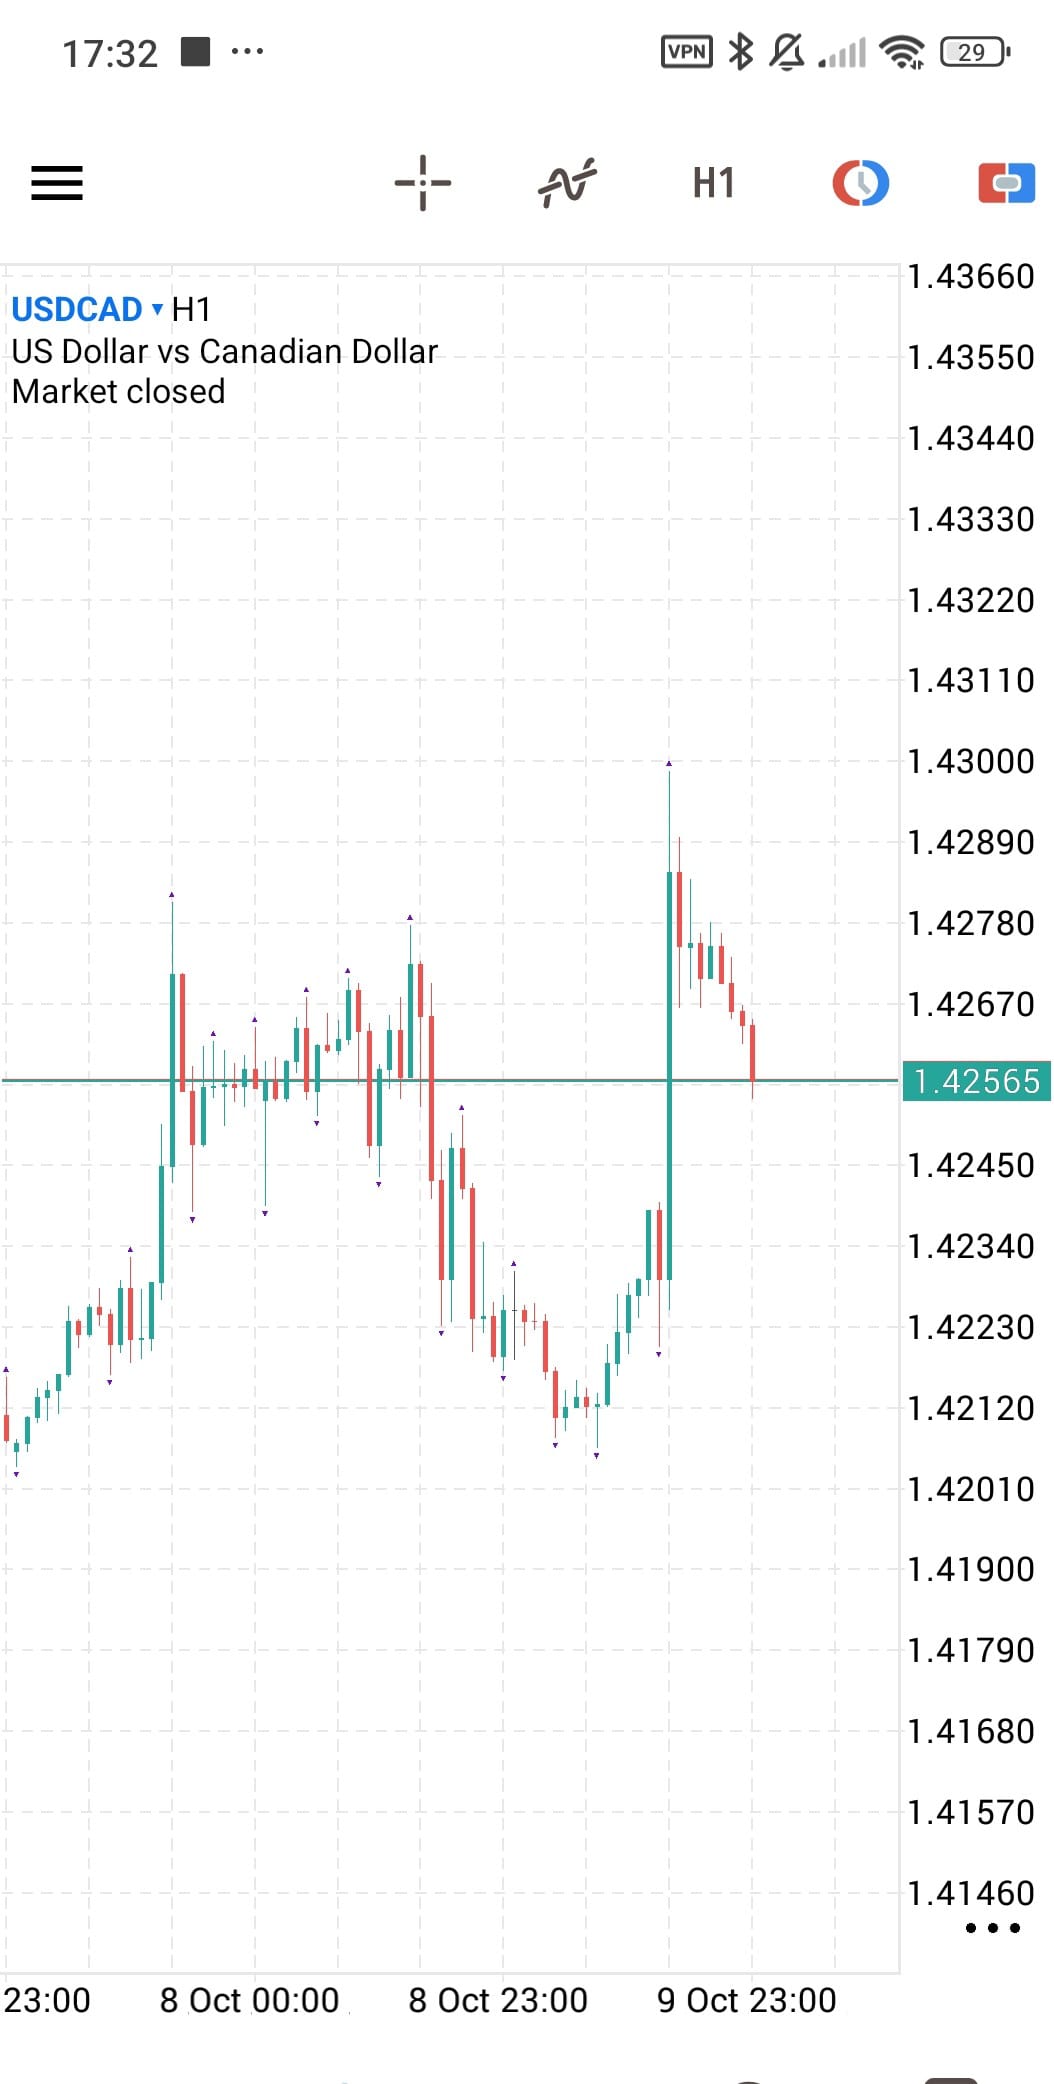
Soft employment data from Canada weakened the CAD on Friday. And speaking of USD pull-backs creating support. I'll have an eye on the chart to see if a nice 1hr up swing forms:
Finally, officials from the US and JAPAN are scheduled to meet during the upcoming week. The market will be on 'heightened intervention watch'. if we do get some sort of coordinated intervention akin to a few weeks ago, all narratives are out of the window (at least for 24 hours) and it becomes traders discretion if the JPY is a long option. Or whether to wait it out until the strength peters out.
On a personal note, following a very good run, I noted a few weeks ago that it's important not to get carried away. Sure enough since then, it's been tough going. This week I placed three trades, Monday's GBP CHF long was closed at break even. Thursday's AUD USD short was also closed at break even (after coming within 1pip of the profit target). Finally, Friday's second bite at AUD USD short stopped out. A slightly frustrating week but we have to take the rough with the smooth.
As much as I'm not keen on it, I'll continue to close trades before end of day to avoid hand-over volatility, I just thinks it's prudent at the moment. Especially with shorter 10 / 15 pip stop losses.
Let's see what the new week brings.
Results
Trade 1: GBP CHF 0
Trade 2: AUD USD 0
Trade 3: AUD USD -1
Total since start of blog = 72.3% (risking 1% per trade).