Weekly Review
Central bank policy took centre stage during the week starting Monday 24 September. Rising oil and rising yields has put rate hikes firmly back on the agenda and the market is trying to guage just how many hikes until each central bank reaches its terminal rate. And if rates continue rising, how long before growth is severely affected?
For now, the mood remains relatively calm, perhaps helped by chair Warsh's suggestion the economy is in a good place and can withstand rate hikes. As things stand, the probability is leaning towards another FED hike before year end, with more to come in 2027. RBA governor Bullock has doubled down on hawkish rhetoric, The BOE, ECB, RBNZ and BOC all look like they have at least one hike on the agenda. The only central bank with no rate hike in sight remains the SNB.
Which brings us to the JPY, leading up to this week's BOJ meeting, the market had started to price in a more aggressive tightening cycle. But, two dissenters and a 'kicking the can down the road' until 'spring wage negotiations' has (once again) disappointed JPY bulls. And I'm (once again) left with a mild JPY short bias, with the caveat that intervention (actual or verbal) could give the yen bouts of strength at any moment.
I shared this image during the week and I think it's fitting to do so again as it currently sums up my thoughts going into the new week:
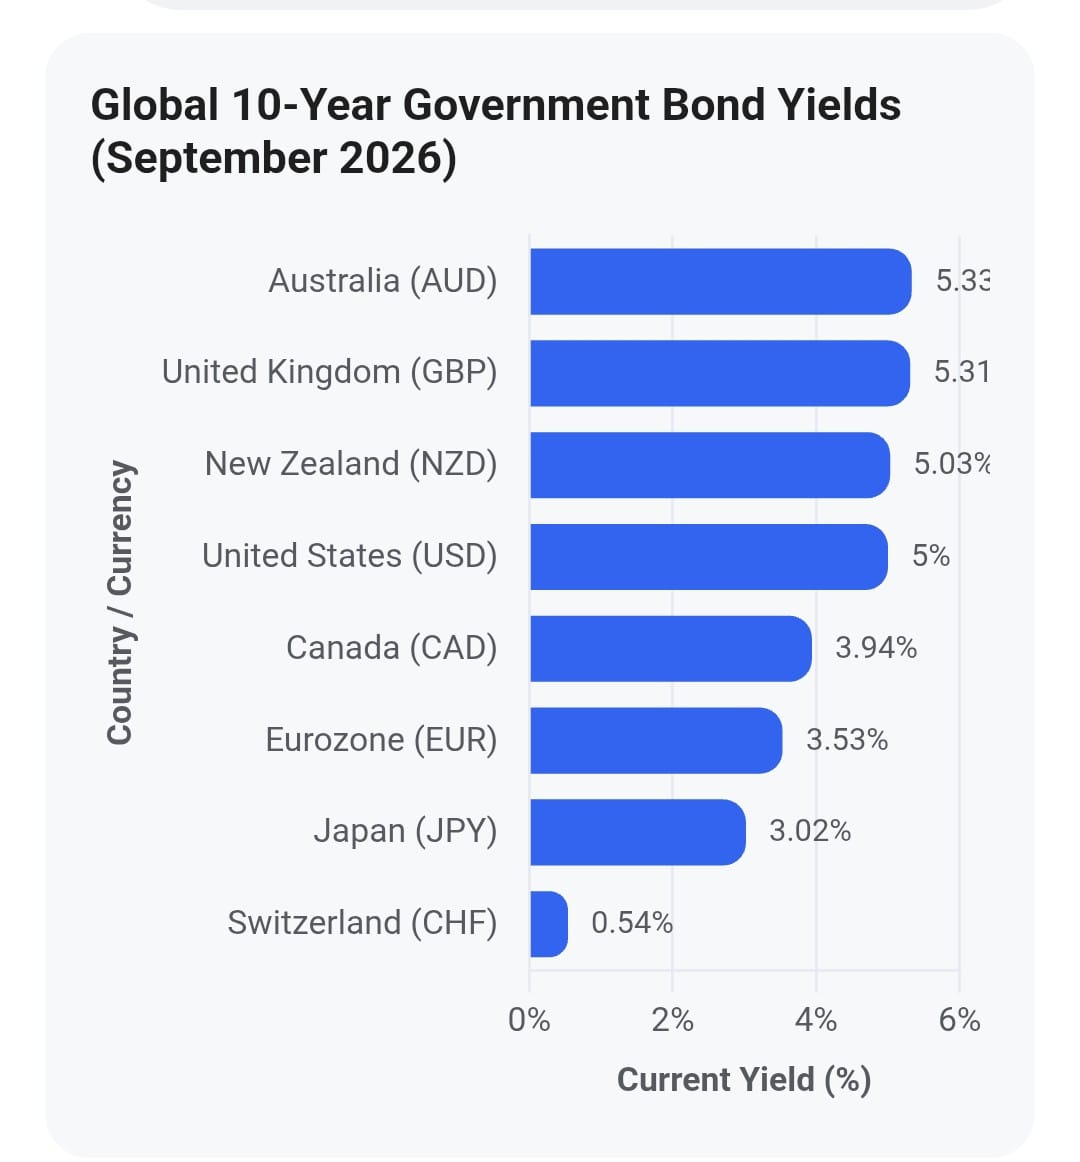
Of course, everything is finely balanced. If the USD / IRAN war ends tomorrow, the price of oil will drop and we'll be talking about rate cuts. Conversely, if the price of oil continues to rise, it won't be long before we are talking about recession. But for now, I begin the new week with an 'interest rate differential bias'.
I'm aware CHF weakness is fairly stretched, therefore I prefer pullbacks creating nice support. It could well be that JPY weakness has further to run but given we've already had suggestions of a 'rate check' on Friday, it's just a question of how tolerant the BOJ will be if USD JPY continues to rise.
On a personal note, my return after a week off was a losing week. I placed three trades, all CHF short. An AUD CHF 4hr support and resistance trade on Monday, which was closed in profit. On Tuesday, with oil on the rise, I traded CAD CHF long, the trade was closed for a small loss before end of day.
Maybe there were opportunities in the immediate aftermath of the FOMC and BOJ meetings. But I waited until Friday to place USD CHF long. The trade stopped out, I'm putting Friday's USD weakness down to profit taking, a) it was Friday, b) following the BOJ rate check. It hasn't (as yet) dented my 'long USD bias'.
One final note: If it was currently a midweek day, I'd be very interested in this chart:
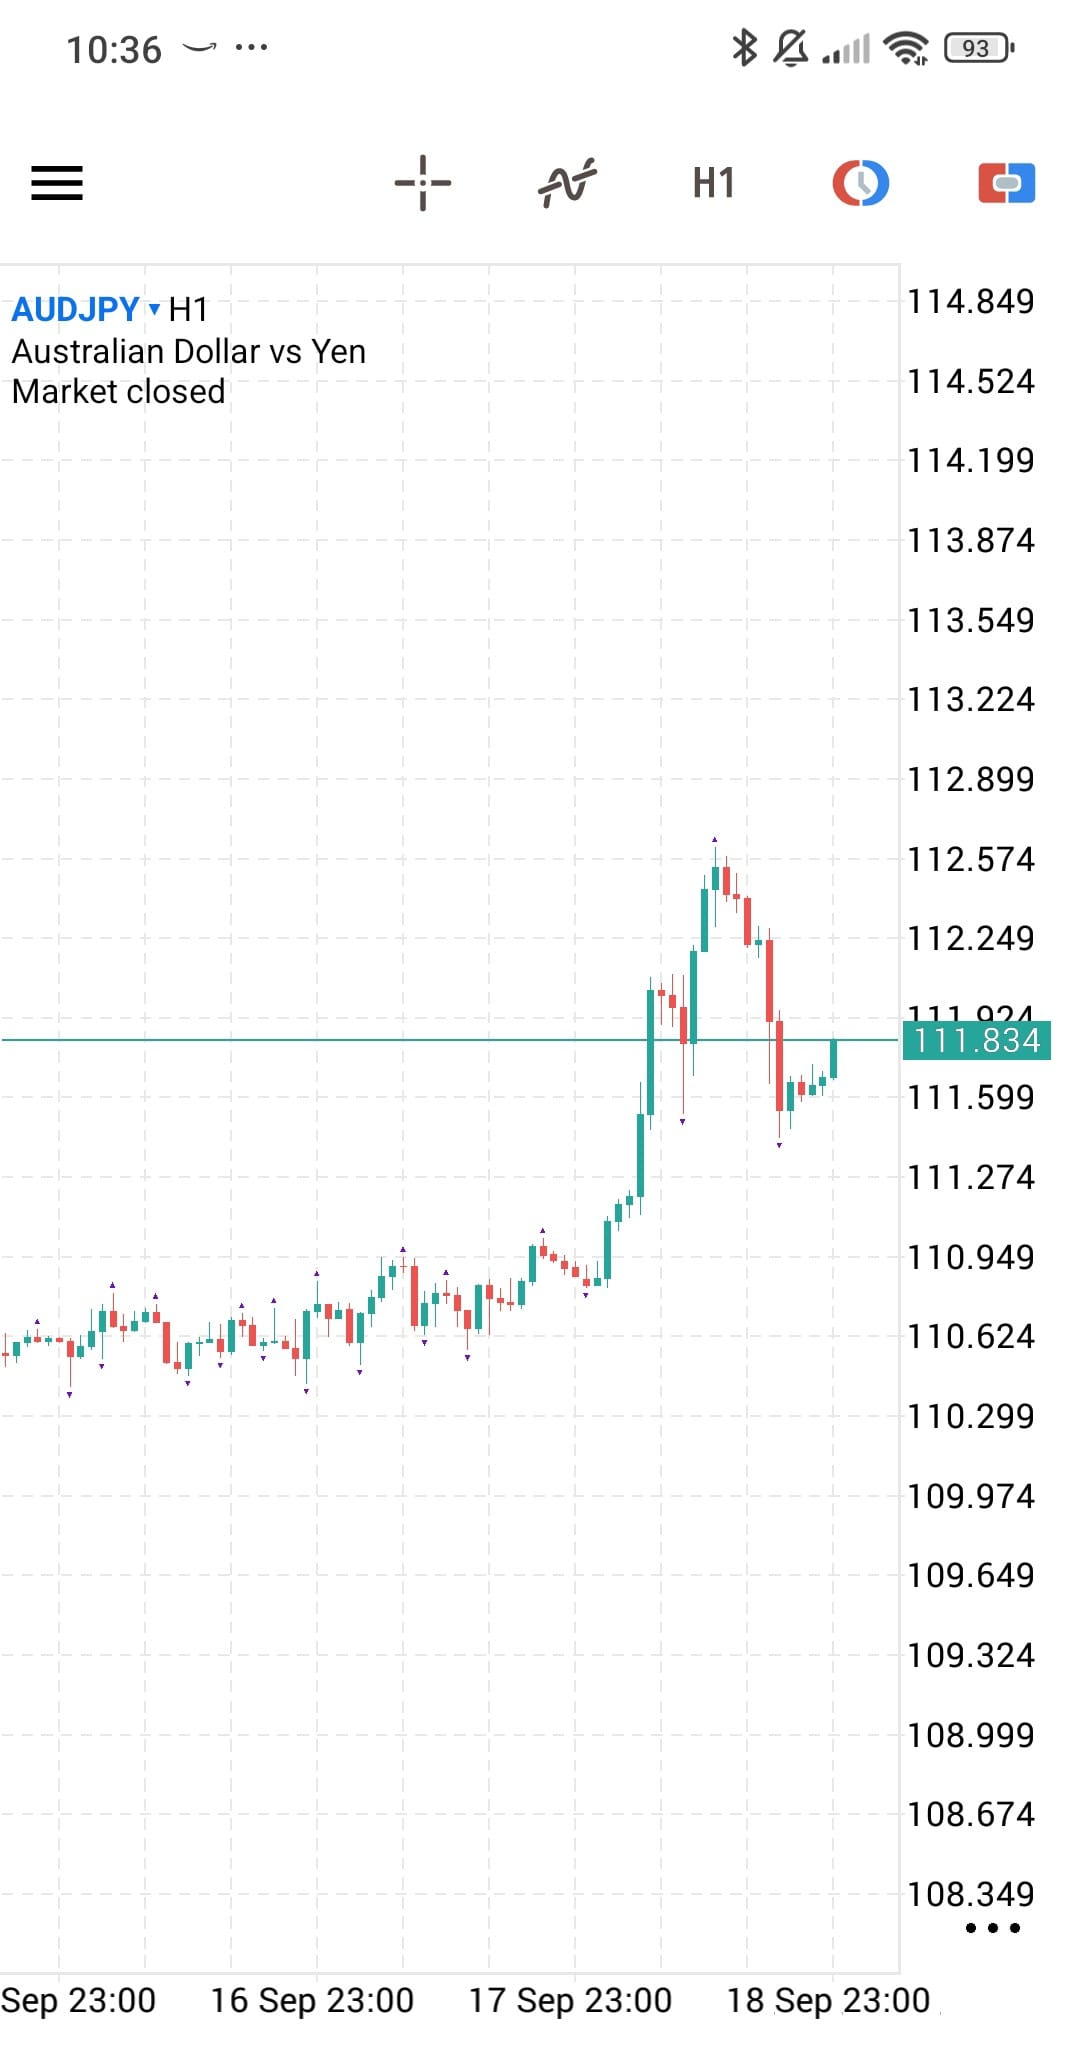
But I'll have to see what it looks like on Monday morning, 'opening gaps' and BOJ rhetoric could paint a very different picture by then.
Please feel free to get in touch with any questions, you may have different opinions me. The only thing that really matters is forming a certainty in your own decision.
Results:
Trade 1: AUD CHF +0.6
Trade2: CAD CHF -0.2
Trade 3: USD CHF -1
Total = - 0.4%
Total since start of blog = +72.4% (risking 1% per trade).